What’s your tree service & arboriculture business worth? Value it in 90 seconds.
Tree Service & Arboriculture businesses are typically priced on one of two earnings figures depending on size: Seller's Discretionary Earnings (SDE) below roughly $1M, and EBITDA above. Applied to tree service & arboriculture specifically, the base multiple ranges are 2.75x–4x SDE and 4.5x–6.5x EBITDA. Where inside that range your business trades is decided by a handful of specific, buyer-visible factors.
Every input stays in your browser. The tool benchmarks each KPI against real Main Street peers in your industry, layers per-KPI multiple lifts on top of the category baseline, and shows a live range with the reasons behind it.
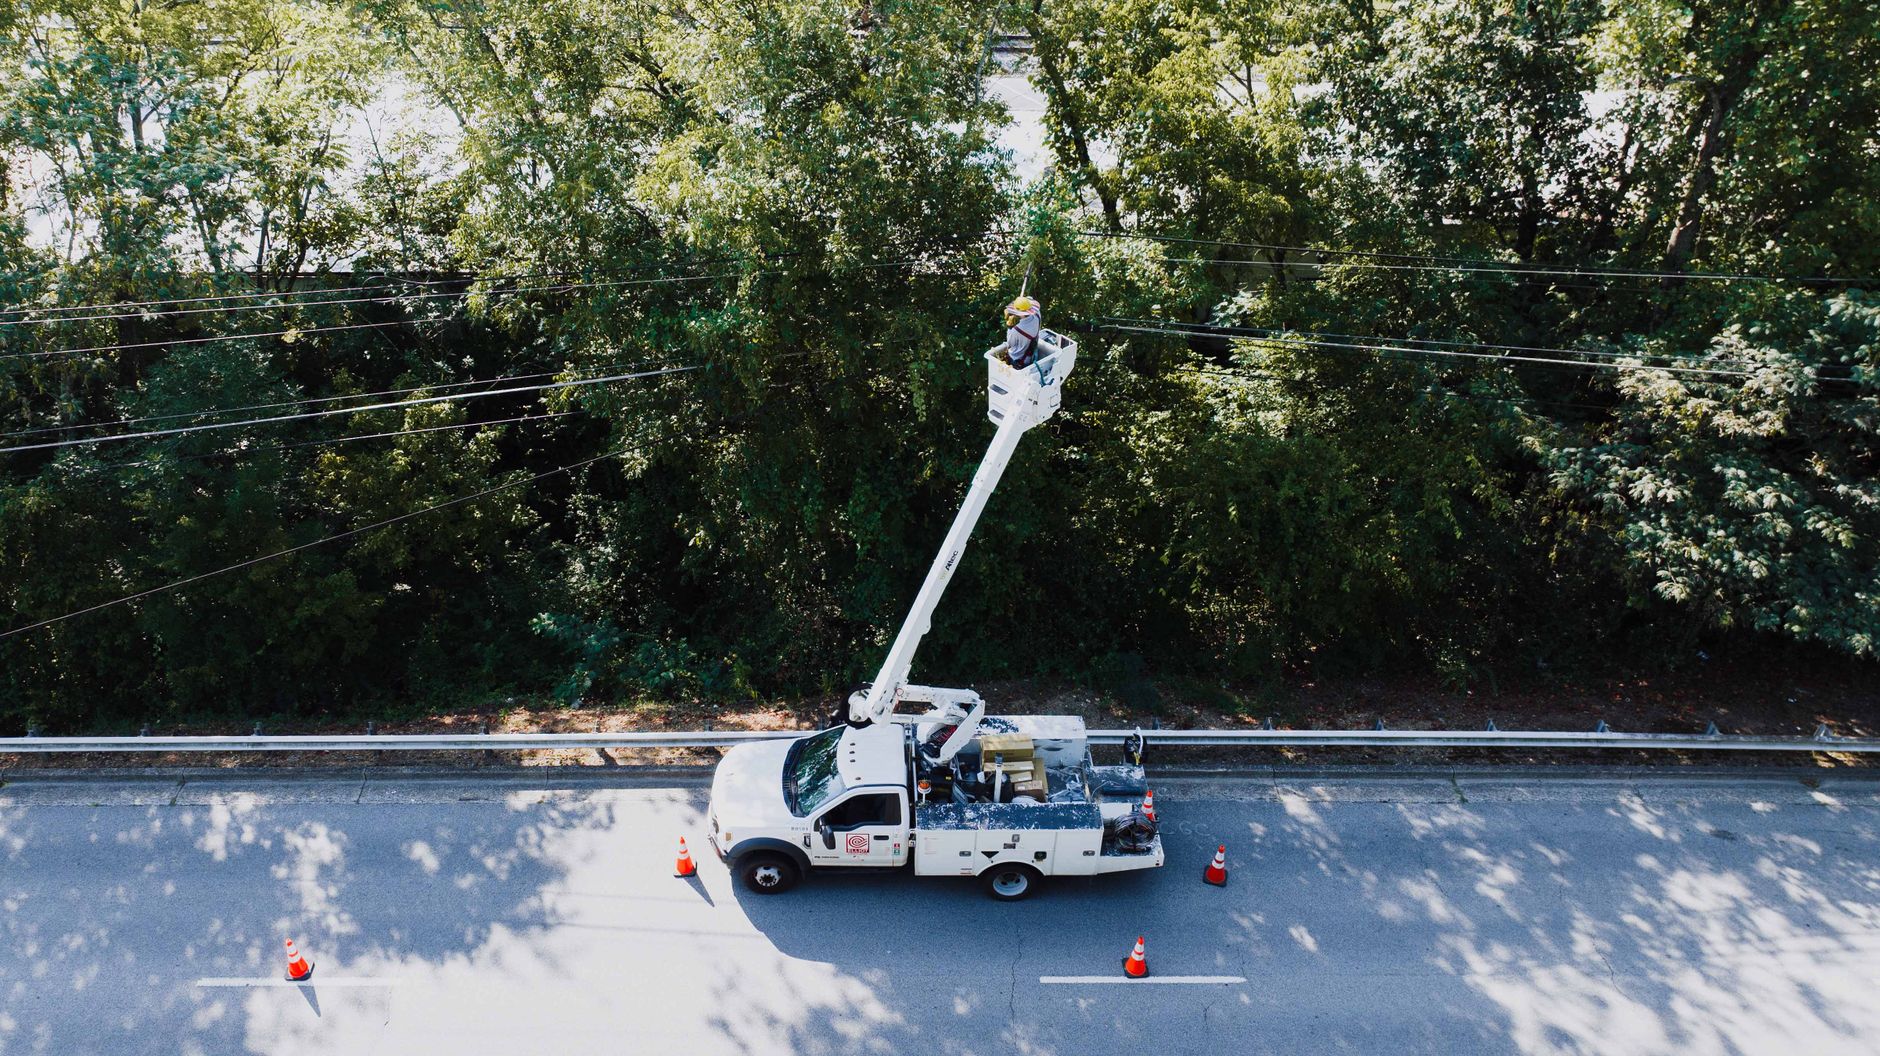
The largest independents (Davey Tree, Bartlett Tree Experts) are strategic acquirers; PE-backed SavATree (Charlesbank Capital Partners) has been an aggressive consolidator, and Monster Tree Service (owned by Authority Brands, which is Apax-backed) leads the franchise side. What's changed materially: plant health care (PHC) contracts — recurring soil injections, deep-root fertilization, insect and disease treatment — have turned traditionally lumpy tree-service revenue into subscription-adjacent revenue, and buyers are paying premiums for operators who've built a real PHC book.
What’s your tree service & arboriculture business worth?
Enter the numbers that actually drive tree service & arboriculture valuations. We benchmark each against real Main Street peers and show you where you land.
What moves the multiple
The metrics buyers actually diligence in tree service & arboriculture.
Category baseline is 2.75x–4x SDE (below ~$1M SDE) transitioning to 4.5x–6.5x EBITDA above. Where inside that range a specific tree service & arboriculture business trades is decided by these operating metrics — the same ones a professional QoE surfaces on day one of diligence.
Plant health care (PHC) revenue percentage
Recurring soil injections, deep-root fertilization, insect and disease treatment. This is the single biggest multiple driver in modern tree service — the subscription-adjacent piece of the business.
ISA-certified arborist count
Number of International Society of Arboriculture certified arborists on staff. Certification is a labor-quality and insurance-underwriting proxy that buyers pay premiums for.
Commercial + utility revenue mix
Recurring commercial accounts (property management, HOAs) and utility line-clearance contracts are meaningfully stickier than one-time residential removals.
Fleet composition
Bucket trucks, chippers, stump grinders, and cranes have long depreciation schedules and are diligence-critical. Fleet age and financing status materially affect deal proceeds.
Insurance loss history + safety record
Tree service has the highest workers-comp mod rating in home services. A clean safety record and low experience-mod are worth real basis points on the multiple.
Deal structure norms
How tree service & arboriculture deals actually close.
Sub-$1M SDE deals close as SBA-financed asset sales with heavy focus on fleet valuation and insurance-loss-history transfer. Above $1M EBITDA, competitive processes with strategic and PE bidders are common — especially for operators with 25%+ PHC revenue in strong residential metros. Deals commonly include 18–24 month transition consulting so the seller can facilitate customer-relationship handoff and, in some states, license/certification transfer.
Recurring-revenue anchor for tree service & arboriculture: 25% of revenue is the threshold that meaningfully lifts multiples. Businesses below that trade nearer the baseline low; above it, buyers underwrite at the top of the range.
Related tools — same industry
Take the numbers further.
Each tool below reads your industry from the URL and pre-seeds the input. No signup.
Sellability score
100-point readiness diagnostic — financials, management, concentration, structure, dependence.
Open toolPredict my buyer
Probability across the five buyer types (Individual, Strategic, Search Fund, PE Consolidator, PE Platform).
Open toolWho buys businesses like mine?
Named active acquirers in your category and the size ranges they underwrite.
Open toolNet proceeds after taxes
Headline price → cash at close after taxes, fees, and seller-note timing.
Open toolNext up
The full tree service & arboriculture sell playbook.
Prep priorities, timing signals, active acquirers, deal structure, and closing — the practitioner playbook specific to tree service & arboriculture deals.
People also ask
Valuing a tree service & arboriculture business.
How is my tree service business valued?
Tree service businesses trade at SDE multiples of 2.75–4.0x for owner-operator books below $1M SDE. Above $1M EBITDA, expect 4.5–6.5x — with the top end reserved for operators with 25%+ plant health care revenue, ISA-certified arborist teams, and clean safety records.How much does plant health care revenue actually move the multiple?
Meaningfully. A tree service operator with 30%+ PHC revenue typically trades at 1.0–1.5 turns higher on the EBITDA multiple than a pure removal-and-pruning book. PHC is the subscription-adjacent piece PE platforms are actually paying premiums for.What kills a tree service deal in diligence?
Three things: (1) workers-comp mod rating above 1.2 signals a safety history buyers will price around, (2) an aged fleet with heavy deferred maintenance or open liens depresses proceeds, and (3) reliance on non-certified crews limits buyer interest to lower-tier acquirers who won't pay the premium multiples.Do utility line-clearance contracts add value?
Yes, if they're bid-won and multi-year. Utility contracts are underwritten by strategic acquirers (Wright Tree, Asplundh-adjacent) very differently than residential work — they value clean bid win-rates and demonstrated safety compliance, and they're willing to pay for it.How accurate is this tree service & arboriculture valuation estimate?
It's an initial diagnostic, not a formal appraisal. The engine uses baseline 2.75x–4x SDE / 4.5x–6.5x EBITDA multiples from published Main Street M&A data, then layers per-KPI adjustments using P25–P90 industry benchmarks. What it can't see is qualitative signal — customer-relationship durability, management-team quality, regulatory risk in your niche. Use it to see where your business lands against peers, then let a specialist broker validate against your actual books before you go to market.
Topic cluster
Business Valuation
How buyers actually price Main Street businesses — SDE and EBITDA multiples, industry benchmarks, and the eight factors that move the number.
Also in this cluster — 9 pages
Business valuation tools
Hub for industry-specific interactive valuation tools with real Main Street KPI benchmarks (P25–P90) — 15 categories covered.
Free exit calculator
Industry-calibrated valuation range in 5 minutes with no signup required.
Business sale multiples dataset
22-industry benchmark table with SDE + EBITDA multiple ranges, days-to-close, and primary buyer types. Free CC BY 4.0 with CSV / JSON / SVG downloads.
Buyer Demand Index
0-100 composite Buyer Demand Score for 150 (metro × industry) tuples across the top 25 U.S. metros and six Main Street industries. Free CC BY 4.0 with CSV / JSON / SVG downloads.
Predict My Buyer
Interactive probability model across the five Main Street buyer types (Individual, Strategic, Search Fund, PE Consolidator, PE Platform). Live results with per-factor transparency.
Sellability score
Score across the five factors buyers actually diligence — financials, management, concentration, structure, dependence.
Net proceeds waterfall
Headline price → cash at close after taxes, fees, and seller-note timing.
Market-wide multiple benchmarks
P25–P75 SDE and EBITDA ranges by industry, sourced from IBBA + BizBuySell.
Main Street industries overview
The macro M&A landscape across home services, professional services, and consumer verticals — where buyer demand is highest and which buyer type is likely to close.
Ready to talk numbers with a human
Validate the estimate with a specialist broker.
Free 30-minute consultation. Sukhrobjon (Rob) Ismoilov or a matched tree service & arboriculture specialist reviews your inputs against the current buyer set.